Markets / Disruption Watch
To Delay or Not to Delay: Was Oura Right to Postpone Its IPO?
Oura’s decision to push back their $2.2B IPO surprised investors. Yet, the move may reflect a strategic effort to secure a stronger valuation and a smoother transition into the public markets.
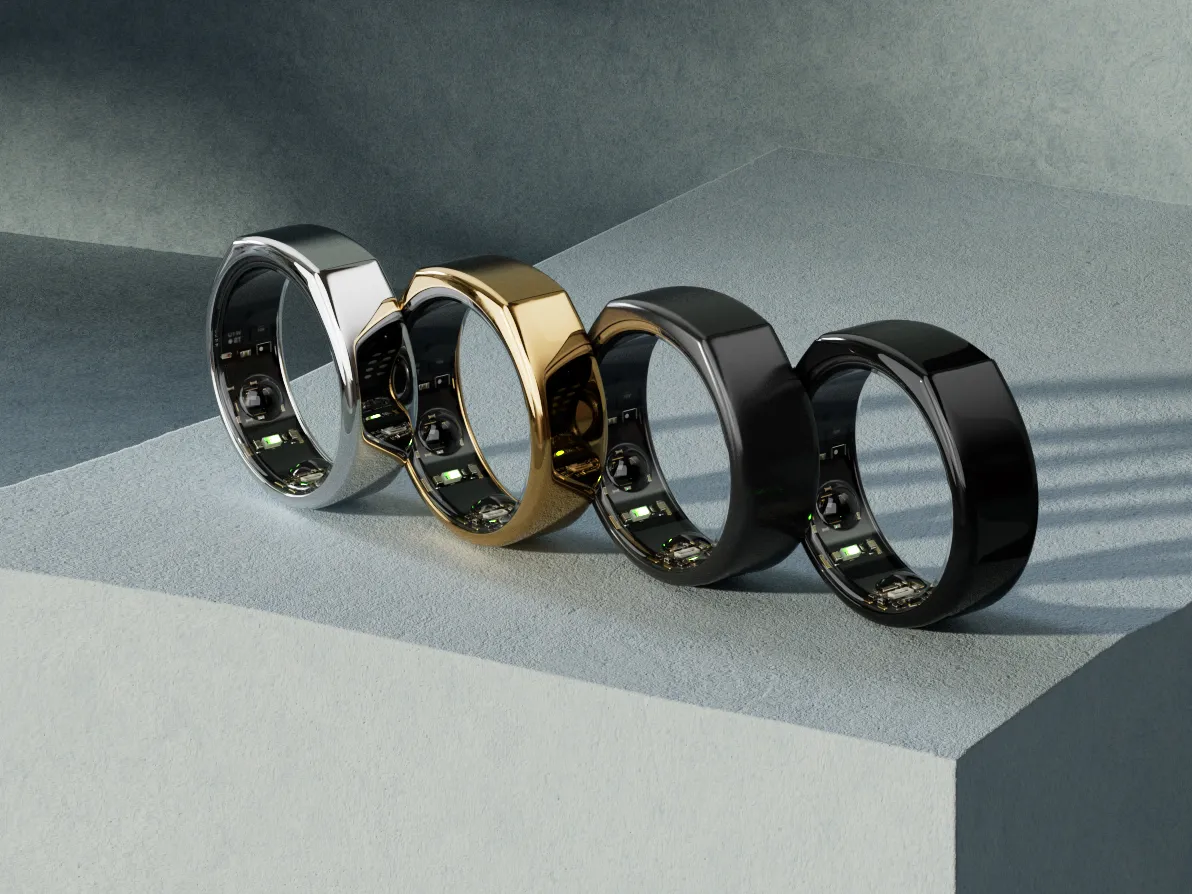
To any investor looking from the outside in, Oura, a fitness-tracking ring company, seems like the perfect candidate for an IPO. With a revenue that has grown from $697.6 million to tabindex="-1",214.5 million and a net income that has soared from tabindex="-1".6 million to $60.8 million between June 30th, 2025 and June 30, 2026 [^1], Oura’s sales are rapidly accelerating while COGS and operating expenses continue to remain under control. Part of this can be linked to a broad trend: with the rise of fitness influencers and the growing importance Millennial and Gen Z consumers place on wellness, this creates a market for global health expected to be worth $278B in 2026. Another part, however, can be attributed to Oura’s many ways of adapting AI to better serve their customers: for example, when battery performance issues were impacting some of their Oura Ring 4 devices, they utilized AI diagnostics to address the increased warranty claims, boosting efficiency while helping maintain customer retention.
Yet, despite these strong results and an already-filed S-1 on September 21st, Oura has decided to delay its IPO. Rather than signaling weakness, this delay may reflect a strategic move to secure a valuation that better reflects long-term growth potential while allowing the firm to wait for more favorable economic conditions. This, in turn, could potentially reduce the risk of a sharp correction in share prices post-IPO.
A Transition Towards More Predictable Revenue
In fact, this delay may be valuable, allowing for a transition towards more predictable streams of revenue: a paid membership for full access to their Oura App. For Oura, these paid fees at $5.99/month or $69.99/year are crucial. Unlike other big technology companies such as Apple, who have lower SG&A costs (only 6% of their revenue) [^4] with an already established long-term customer base, Oura’s SG&A expenses make up 21% of revenue [^1], with customer acquisition costs increasing $44.3M between over the past year [^1]. Therefore, more time to increase subscription revenue allows them to compensate for the higher customer acquisition costs that come with being a relatively newer company.
| Revenue (in thousands of $) | 6/30/2026 | 6/30/2025 |
|---|---|---|
| Hardware | 973,980 | 588,726 |
| Membership | 240,526 | 108,843 |
| Revenue (in thousands of $) | 9/30/2025 | 9/30/2024 |
|---|---|---|
| Hardware | 743,393 | 331,203 |
| Membership | 158,463 | 75,548 |
To this end, Oura has already made progress. Subscription revenue increased from a low of 16% of sales as of June 30th, 2025 to 20% as of June 30th, 2026 [^1], their highest monetary amount yet. At the same time, the number of rings and paid memberships continues to expand, a good indicator to investors that subscription growth comes with and not at the expense of demand for Oura’s core product.
| Number of Sales | 6/30/2026 | 6/30/2025 |
|---|---|---|
| Rings Sold | 3.1m | 1.8m |
| Paid Members | 5.0m | 2.5m |
| Number of Sales | 9/30/2025 | 9/30/2024 |
|---|---|---|
| Rings Sold | 2.3m | 1.0m |
| Paid Members | 2.9m | 1.3m |
If this trend continues, recurring subscriptions create more predictable streams of revenue that can reduce uncertainty on future cash flows, which may persuade investors to give a higher valuation. Altogether, the delay and potential increase in membership revenue could offset a primary risk repeatedly emphasized throughout their S-1: “This rapid growth may not be sustainable or indicative of future performance, and we expect our growth rate to slow over time.” [^1]
A Clearer Picture of AI’s Impact on Profits
In terms of more stable long-run operations, another key factor for Oura to consider is their AI features. For example, Oura Advisor is their AI companion that can generate recommendations for sleep, managing stress, fitness recovery, etc, based on tracked health data and is something only available by purchasing a subscription. That, plus their Oura Women’s Health Expert is an LLM that can provide recommendations to optimize health for women based on their goals and can even adapt based on natural cycles, fertility goals, and menopause. Between both of these innovations, Oura has unique features that can help them maintain current subscribers and attract new ones, especially as women make up 72% of all Oura members [^1]. However, because Oura Advisor was launched in April 2025 and Women’s Health Expert in February 2026, there is insufficient evidence to strongly corroborate the hypothesis that these AI features help with customer acquisition and retention in the long-run. For investors, this makes it difficult to determine how much value to assign to these AI features, which could have serious implications for Oura’s pricing.
If investors underestimate Oura Advisor’s role in profitability, Oura may raise less capital than needed, creating potential financial constraints on future projects or promotions crucial to further expansion of the company. On the other hand, if investors overestimate Oura Advisor’s impact, share prices may be inflated and eventually experience a volatile drop. And with worries of an AI bubble similar to that of the dotcom crash, companies face greater market pressure to prove that incorporating AI into their products can be used to generate actual profits as opposed to just being a marketing tactic. By waiting, Oura would gain the opportunity to further refine Oura Advisor and show that this new feature does indeed meaningfully contribute to paid membership before investors attribute a value to it.
A Currently Unfavorable Combination of Macroeconomic Conditions
However, even if Oura can successfully raise subscription revenue and demonstrate that its investments in AI support long-term growth, it would still have to contend with unfavorable macroeconomic conditions. In fact, the Federal Reserve recently raised rates by 0.25%, with a dot plot revealing that 12 officials expect another quarter-point increase and four expect for a two-quarter point increase[^2]. The Federal Reserve has also removed the predicted 2027 rate cut[^2], implying that interest rates will most likely be increasing into the foreseeable future. As a result, borrowing for business becomes more expensive, potentially limiting company launches and other strategic initiatives that could maintain a stable valuation beyond IPO.
Apart from the interest rate hike, the 10-year Treasury yield has now reached its highest levels in 19 years at 5.00%[^3]. Higher treasury yield rates mean lower IPO values because when yields increase, investors demand higher returns to compensate for riskier investments while also being more attracted to safer investments like bonds, thus raising the cost of capital for Oura if it were to go public when originally planned. As such, postponing the IPO would allow Oura to enter when the economic conditions can provide an environment more supportive of a valuation that better reflects its strong financial performance.
Potential Risks of Delaying and Oura's Mitigation
That said, there are some potential risks with Oura's decision to delay their IPO. With this delay, their biggest competitors may leverage this as a chance to develop their own AI technologies, potentially weakening Oura's own market differentiation. Apple, for example, is in the process of beta testing new Audio Intelligence technology that on top of allowing users to record conversations and rewind, can " help...identify important sounds...from their watch, while the song recognition feature taps into Apple’s Shazam app to detect music playing in the background and identify the song name and artist."[^5]
However, Oura’s AI features remain unique in that they allow all users to receive and tailor recommendations and appeal to one of their biggest demographics: women. Moreover, their hardware product is much more lightweight, easily worn, and overall, less invasive during daily activities for consumers, which will continue to be a strong selling point. Therefore, given Oura's history of gradually releasing new features, it is expected that their R&D teams will continue to add and improve their products, potentially mitigating these risks.
From this perspective, with Oura’s growing paid membership client base, recently launched AI features, and still challenging market conditions, waiting may prove to be the right decision at the right time. After all, if these factors play out in Oura’s favor, pushing back its IPO will be remembered as a strategic advantage, not a setback.
[^1]: Oura Inc. Amendment No.1 to Form S-1 Registration Statement. U.S. Securities and Exchange Commission, Sept. 21, 2026
[^4]: Rachel Barber, Medora Lee, Daniel de Visé, Jessica Guynn. “Fed raises rates for first time since 2023. What it means for you.” USA Today, Sept. 16, 2026
[^3]: Lee Ying Shan, Sean Conlon. “10-year Treasury yield hits highest level since 2007 as traders bet a Fed rate hike is coming.” CNBC, Sept. 15, 2026
[^2]: Apple Inc., Form 10-K for the fiscal year ended September 26, 2026 (Cupertino, CA: Apple Inc., 2026), Nov. 3, 2026.
[^5]: Maxwell Zeff, "Apple Watch's AI Features for Rewinding and Recapping Conversations Begin Beta Testing," TechCrunch, November 2, 2026.